


Perpetual vs Periodic Inventory: Which Fits Your Warehouse?
Perpetual inventory updates the record at every transaction, so the system always holds a number for what is on the shelf. Periodic inventory updates the record only when someone counts, and holds no live figure in between. Most warehouses that ship every day, or that publish a stock level to any channel, need perpetual to operate. But perpetual does not end physical counting, and it does not by itself decide how inventory is valued at year end.
Perpetual inventory updates the stock record at the moment of every transaction: a receipt, a putaway, a pick, a transfer, an adjustment. Periodic inventory updates the record only when somebody counts, and holds no live figure in between. For a warehouse that ships every day, the operational answer is almost always perpetual. The useful question is not which one sounds more modern, but which one you are actually running today, and what it would cost to change that.
What each method actually does
Under a periodic system, the stock figure is a snapshot with a date on it. You count, you write the number down, and the record does not move again until the next count; purchases accumulate separately. At period end you count again, and cost of goods sold falls out as the residual: opening stock, plus purchases, minus closing stock. Between counts the system holds no live figure at all, only whatever estimate someone makes by hand.
Under a perpetual system, every movement is a transaction against the record. Receive twelve cases, the record goes up by twelve. Pick three units, it goes down by three. The record is always populated, always addressable, and always slightly wrong in the way that all live records are slightly wrong: it reflects what was recorded, not what happened.
Periodic is wrong between counts and you know it. Perpetual is wrong in ways you do not know about until you count.
Two decisions wearing the same name
Perpetual versus periodic is usually presented as one choice. It is two, and they are made by different people.
The first is operational: does your system know, right now, how many units sit in a given location? Without that you cannot allocate stock to an order, promise a ship date, or tell a customer whether you have something.
The second is fiscal: how is inventory recognised and valued for tax and reporting? That is governed by the tax code and your accountant, not by your warehouse software. US regulation states the general rule plainly: inventories "at the beginning and end of each taxable year are necessary in every case in which the production, purchase, or sale of merchandise is an income-producing factor" (26 CFR 1.471-1). That general rule is subject to a small business taxpayer exception, covered further down. Where inventories are kept, the IRS recognizes specific identification, FIFO and LIFO for identifying items, and cost, lower of cost or market, and the retail method for valuing them (Publication 538). Those are not freely interchangeable, and which are available to you is your accountant's call rather than your WMS's.
None of those words are the words on your WMS dashboard. You can run a fully perpetual floor system and still close the books with a single year-end valuation. Conflating the two is how a warehouse manager ends up in a meeting arguing about FIFO when one person means picking sequence and the other means cost flow.
Perpetual does not mean you stop counting
This is the promise that gets oversold, and the audit standards are unusually blunt about the condition attached to it.
The PCAOB's standard for audits of public companies treats perpetual records and physical counts as a pair rather than as alternatives. Where a company keeps perpetual records and checks them against reality, the auditor gets flexibility on timing: "when the well-kept perpetual inventory records are checked by the client periodically by comparisons with physical counts, the auditor's observation procedures usually can be performed either during or after the end of the period under audit" (PCAOB AS 2510). The same standard allows the client to use statistical sampling in taking a physical inventory, where the sampling plan is reasonable, statistically valid and properly applied.
Most privately held warehouses will never be audited under that standard. The logic still transfers, because it is not an accounting artefact: the condition is the only reason anyone believes the number. And the sampling provision is the operational door — counting a valid sample rather than the whole building is what makes a continuous programme affordable in the first place.
So the reward for keeping good perpetual records is not the end of counting. It is that counting stops being one enormous event on the last weekend of the year and becomes a small continuous program you run without closing the building. Cycle counting is the mechanism, and the choice between cycle counting and a full physical count is worth understanding on its own terms: see cycle count vs physical inventory.
A perpetual system with no counting program behind it is still perpetual. It is just unverified, and an unverified number gets acted on exactly as confidently as a true one.
Where perpetual actually gets expensive
The line item is the licence. The cost is that every transaction point becomes a place where accuracy is created or destroyed, and each one needs a written procedure and a person who follows it.
- Receiving. Where an error is cheapest to catch and most expensive to miss, because everything downstream inherits it.
- Putaway. A unit in an unrecorded location is functionally missing, even though it is in the building and on the books.
- Picking. Short picks, substitutions and "I grabbed it from the other shelf" are the daily erosion.
- Returns and transfers. Stock re-entering the pickable pool is the point most often left without a procedure.
- Adjustments. An adjustment without a reason code is a number you will spend an afternoon reconstructing instead of a minute.
The common thread is capture at the moment of the move. Whether that capture is a scan or a keystroke matters less than whether it happens at the event or from memory at the end of the shift, though scans fail less often and fail in ways you can find. If you want the mechanics, barcode scanning in the warehouse covers the capture points, and what inventory accuracy actually measures covers how to tell whether any of it is working.
When periodic is still the right answer
Periodic is not a historical curiosity. It remains reasonable when:
- The catalog is small and homogeneous, and stock sits in one place a person can see.
- Unit value is low and the consequence of being wrong is a reorder, not a failed shipment.
- Nothing downstream consumes the stock number in real time. No storefront, no marketplace, no promise date.
- Consumables or supplies are being tracked for budget rather than for fulfilment.
If any system outside your four walls publishes your stock level to a customer, periodic stops being viable. Not because the method is bad, but because the number gets read by people who will act on it before your next count.
How to tell which one you are actually running
It is common to answer "perpetual" and run something in between. Three questions settle it:
- If you pick a location at random right now, does the system hold a quantity for it, and would you bet on that quantity being right?
- When a count finds a discrepancy, does anyone find out why, or does the system simply get overwritten with the counted number?
- Between counts, does the number move because of recorded events, or because someone typed it?
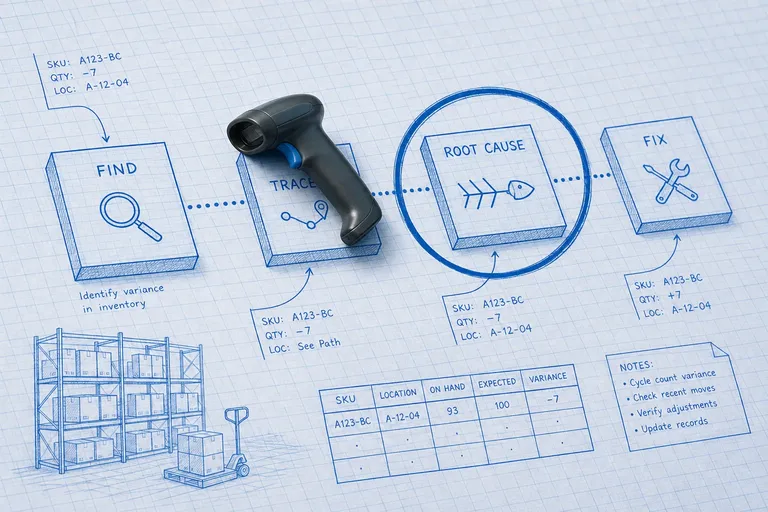
Locations and pick paths are a precondition for perpetual, not evidence of it; plenty of warehouses have both and still run on printed batch tickets with no live quantity behind them. And if discrepancies are absorbed silently, the record gets corrected and nobody asks which transaction point broke. The variance is the only signal telling you that, which is where most of the value of perpetual actually sits.
Where the tax question ends and the operations question begins
Worth knowing before you justify a warehouse process on tax grounds. Under the small business taxpayer exception, a qualifying business may choose not to keep an inventory, provided it still uses a method of accounting for inventory that clearly reflects income (Publication 538). The election is not "stop tracking stock": Publication 334 sets out what it actually requires, including treating inventory as non-incidental materials and supplies, or conforming to the treatment in your books. Eligibility runs on a gross receipts test, and for tax years beginning in 2026 the figure is average annual gross receipts of $32 million over the three prior tax years (Rev. Proc. 2025-32, section 4.30).
None of that is tax advice, and your accountant decides what applies to your entity. The point is narrower: if you need perpetual records, you need them because you cannot promise a ship date without them. That argument stands on its own and does not depend on a filing requirement.
If you are moving from periodic to perpetual
Fix the process before the software, in this order:
- Count once, properly, and start from a known number. A perpetual record seeded from a bad baseline inherits the error until a count finds it.
- Name every location. Perpetual records track quantity at a place. Without addressable locations you get a SKU-level total, which is enough for the books and not enough for a pick.
- Make receiving the control point. Quantity, and lot or expiry where they apply, captured at the door before putaway.
- Give every adjustment a reason code. A small, enforced list. This is what turns variance into a diagnosis.
- Start the cycle count program on day one, not after the implementation settles. The program is what keeps the record true; adding it later means months of drift to unwind.
The order matters. Software installed on top of an unaddressed floor produces a very fast, very precise account of something that is not happening.
Frequently asked questions
Does a perpetual inventory system mean I never have to count again?
No. Perpetual records tell you what should be on the shelf; only a count tells you what is. The PCAOB's standard for public-company audits links the two directly: where perpetual records are well kept and are periodically compared with physical counts, an auditor's observation procedures can usually be performed during the period rather than only at year end. That flexibility is conditional on the counting actually happening.
Is perpetual versus periodic an accounting decision or an operations decision?
Both, and they are separate decisions that share a name. Operationally it is about whether your system updates stock at every transaction. For tax, the question is whether you must keep inventories at all and how they are valued, which turns on your gross receipts and on whether merchandise is an income-producing factor. You can run a perpetual warehouse system and still value inventory only at year end.
Do small businesses have to keep an inventory for tax purposes?
Not always. Under the small business taxpayer exception at section 471(c), a qualifying business can choose not to keep an inventory, provided it still uses a method of accounting for inventory that clearly reflects income. Eligibility runs on a gross receipts test: for tax years beginning in 2026 the figure is average annual gross receipts of $32 million over the three prior tax years. Your accountant decides whether it applies to you.
Plan the route. We deliver the rest.
See how Binlogic powers last-mile logistics — routing, tracking, and the platform that turns the plan into the package on the doorstep.
Book a callback